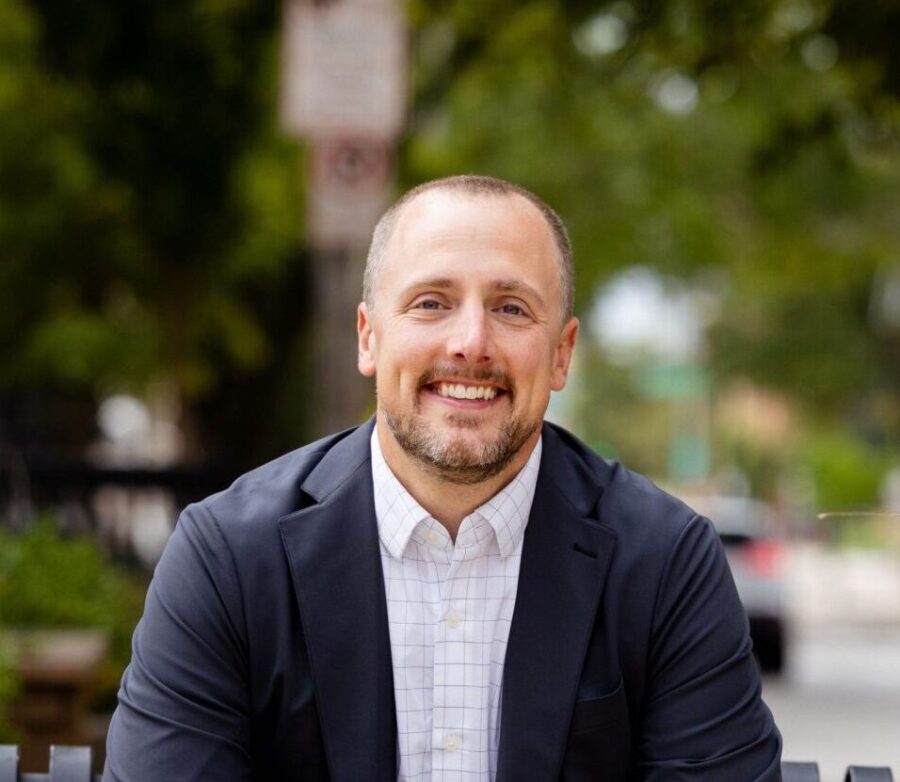
Kevan Melchiorre, CFP®, Co-Founder of Tenet Wealth Partners, recently shared his perspective with CNBC on the role of 401(k)s in retirement planning, how much workers may consider saving, and why feeling behind doesn’t mean it’s too late to revisit your retirement savings approach.
This article references Kevan’s recent feature in CNBC Make It, written by Mike Winters. Read the CNBC article here.
Recent Fidelity data highlighted by CNBC found that the average 401(k) balance among its participants was $75,200 for those in their 30s and $156,800 for those in their 40s. Workers were also saving an average of 14.4% of their pay when employer contributions were included.
Those numbers can provide useful context, but averages and age-based benchmarks only tell part of the retirement planning story.
Your 401(k) balance is one way to measure your progress, but it doesn’t necessarily tell you whether you are saving enough for your individual retirement goals. Your other investment accounts, income, anticipated retirement date, spending needs and broader financial circumstances can all play a role.
When speaking with CNBC, Kevan discussed several considerations for evaluating retirement savings, from making the most of an employer match to looking beyond a single account balance.
Making the Most of Your 401(k)
For many workers, a 401(k) is one of the primary tools available for building retirement savings. When an employer provides a matching contribution, understanding how that match works can be an important part of determining how much to contribute.
As Kevan shared with CNBC, “A 401(k) is a fantastic retirement savings tool for a lot of reasons.”
Contributing enough to receive an available employer match, however, doesn’t necessarily answer the broader question of how much you should be setting aside for retirement.
Earlier in your career, establishing a consistent savings habit can provide a useful foundation. As your income and financial circumstances evolve, it may also make sense to periodically revisit your contribution rate rather than setting it once and leaving it unchanged for years.
That review can include questions such as whether you are taking full advantage of an available employer match, whether your savings rate has kept pace with changes in your income, and how your 401(k) fits alongside the other accounts you are using for retirement.
Look Beyond Your 401(k)
Your 401(k) may be an important part of your retirement savings, but it may not be the only account contributing to your longer-term plan.
IRAs, taxable investment accounts and other savings may also factor into the picture. Looking across these accounts can provide a broader view than evaluating your 401(k) balance on its own.
In speaking with CNBC, Kevan noted that a general rule of thumb is to consider saving at least 15% of income for retirement across investment accounts, including employer 401(k) contributions.
That figure is a starting point, not a universal target. Your career stage, current savings, anticipated retirement date, spending expectations and other financial priorities can all affect an appropriate savings approach.
This is also why comparing your 401(k) balance directly with an age-based average can have limitations. Two people of the same age with identical 401(k) balances could have very different financial circumstances and retirement goals.
Rather than viewing any single benchmark in isolation, consider periodically reviewing your overall retirement savings and whether your current approach continues to align with the future you are planning for.
What If You Feel Behind on Retirement Savings?
Retirement savings benchmarks can provide perspective, but they can also feel discouraging when your savings don’t resemble the numbers you see reported for your age group.
For workers in their 40s who feel behind, there may still be decades before retirement to continue saving and investing. While beginning earlier provides more time for investments to potentially grow, starting later does not mean there is nothing you can do.
As Kevan told CNBC, “The biggest mistake is assuming it’s too late and getting discouraged to start.”
Rather than focusing exclusively on where you think you should have been, consider what you can reasonably do today. That might mean reviewing your current contribution rate, contributing what your circumstances allow and considering whether you can gradually increase that amount over time.
Your savings capacity may also change. Income can rise, debts may be paid down and other expenses can shift. Revisiting your retirement contributions as those circumstances change can help keep your savings strategy connected to your broader financial plan.
Ultimately, retirement benchmarks are reference points, not individualized financial plans. Whether you are in your 30s and building momentum or in your 40s and reassessing your progress, understanding where you stand today can help you determine what adjustments, if any, may make sense for your longer-term goals.
Investment advisory services offered through Tenet Wealth Partners, LLC, a registered investment advisor with the U.S. Securities and Exchange Commission. This material is intended for informational purposes only. It should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney or tax advisor. This information is not an offer or a solicitation to buy or sell securities. The information contained may have been compiled from third-party sources and is believed to be reliable.
The information provided in this communication was sourced by Tenet Wealth Partners through public information and public channels and is in no way proprietary to Tenet Wealth Partners, nor is the information provided Tenet Wealth Partner’s position, recommendation or investment advice. This material is provided for informational/educational purposes only. This material is not intended to constitute legal, tax, investment or financial advice. Investments are subject to risk, including but not limited to market and interest rate fluctuations.
Any performance data represents past performance which is no guarantee of future results. Prices/yields/figures mentioned herein are as of the date noted unless indicated otherwise. All figures subject to market fluctuation and change. Additional information available upon request.
About The Author
Kevan Melchiorre, CFP®Co-Founder & Managing Partner
Kevan Melchiorre co-founded Tenet Wealth Partners in 2021 with a focus on delivering a premier client experience, supported by an innovative and fully integrated approach to wealth planning. As a CERTIFIED FINANCIAL PLANNER® practitioner with over 18 years of wealth management experience, Kevan partners with affluent individuals, families, and institutions to help align their capital […]
Learn more about Kevan