Throughout much of stock market history, investing centered primarily on the selection of individual stocks and bonds. Over recent decades, however, macroeconomic (“big picture” economy) developments have come to exert an increasingly powerful influence on markets. Major events — whether tied to central bank decisions, geopolitical tensions, or shifts in global trade — now ripple across virtually all stocks, regardless of their individual fundamentals. For investors, this reality means that constructing modern portfolios is less about identifying attractive individual securities and more about making asset allocation decisions that align with long-term financial goals.
This dynamic has been on full display over the past year and a half, during which the two most significant macroeconomic forces have been the war in Iran and U.S. tariff policy. Although these are distinct in nature, both carry implications for consumer prices and business activity — one through elevated energy costs and the other through the price of imported goods. Historically, a defining feature of these macro-driven events, however, is that their effects tend to diminish over time. For this reason, investors are best served by keeping their focus on longer-term trends and resisting the urge to react to any single development with portfolio changes.
Middle east conflict, pump prices, and the shifting role of OPEC
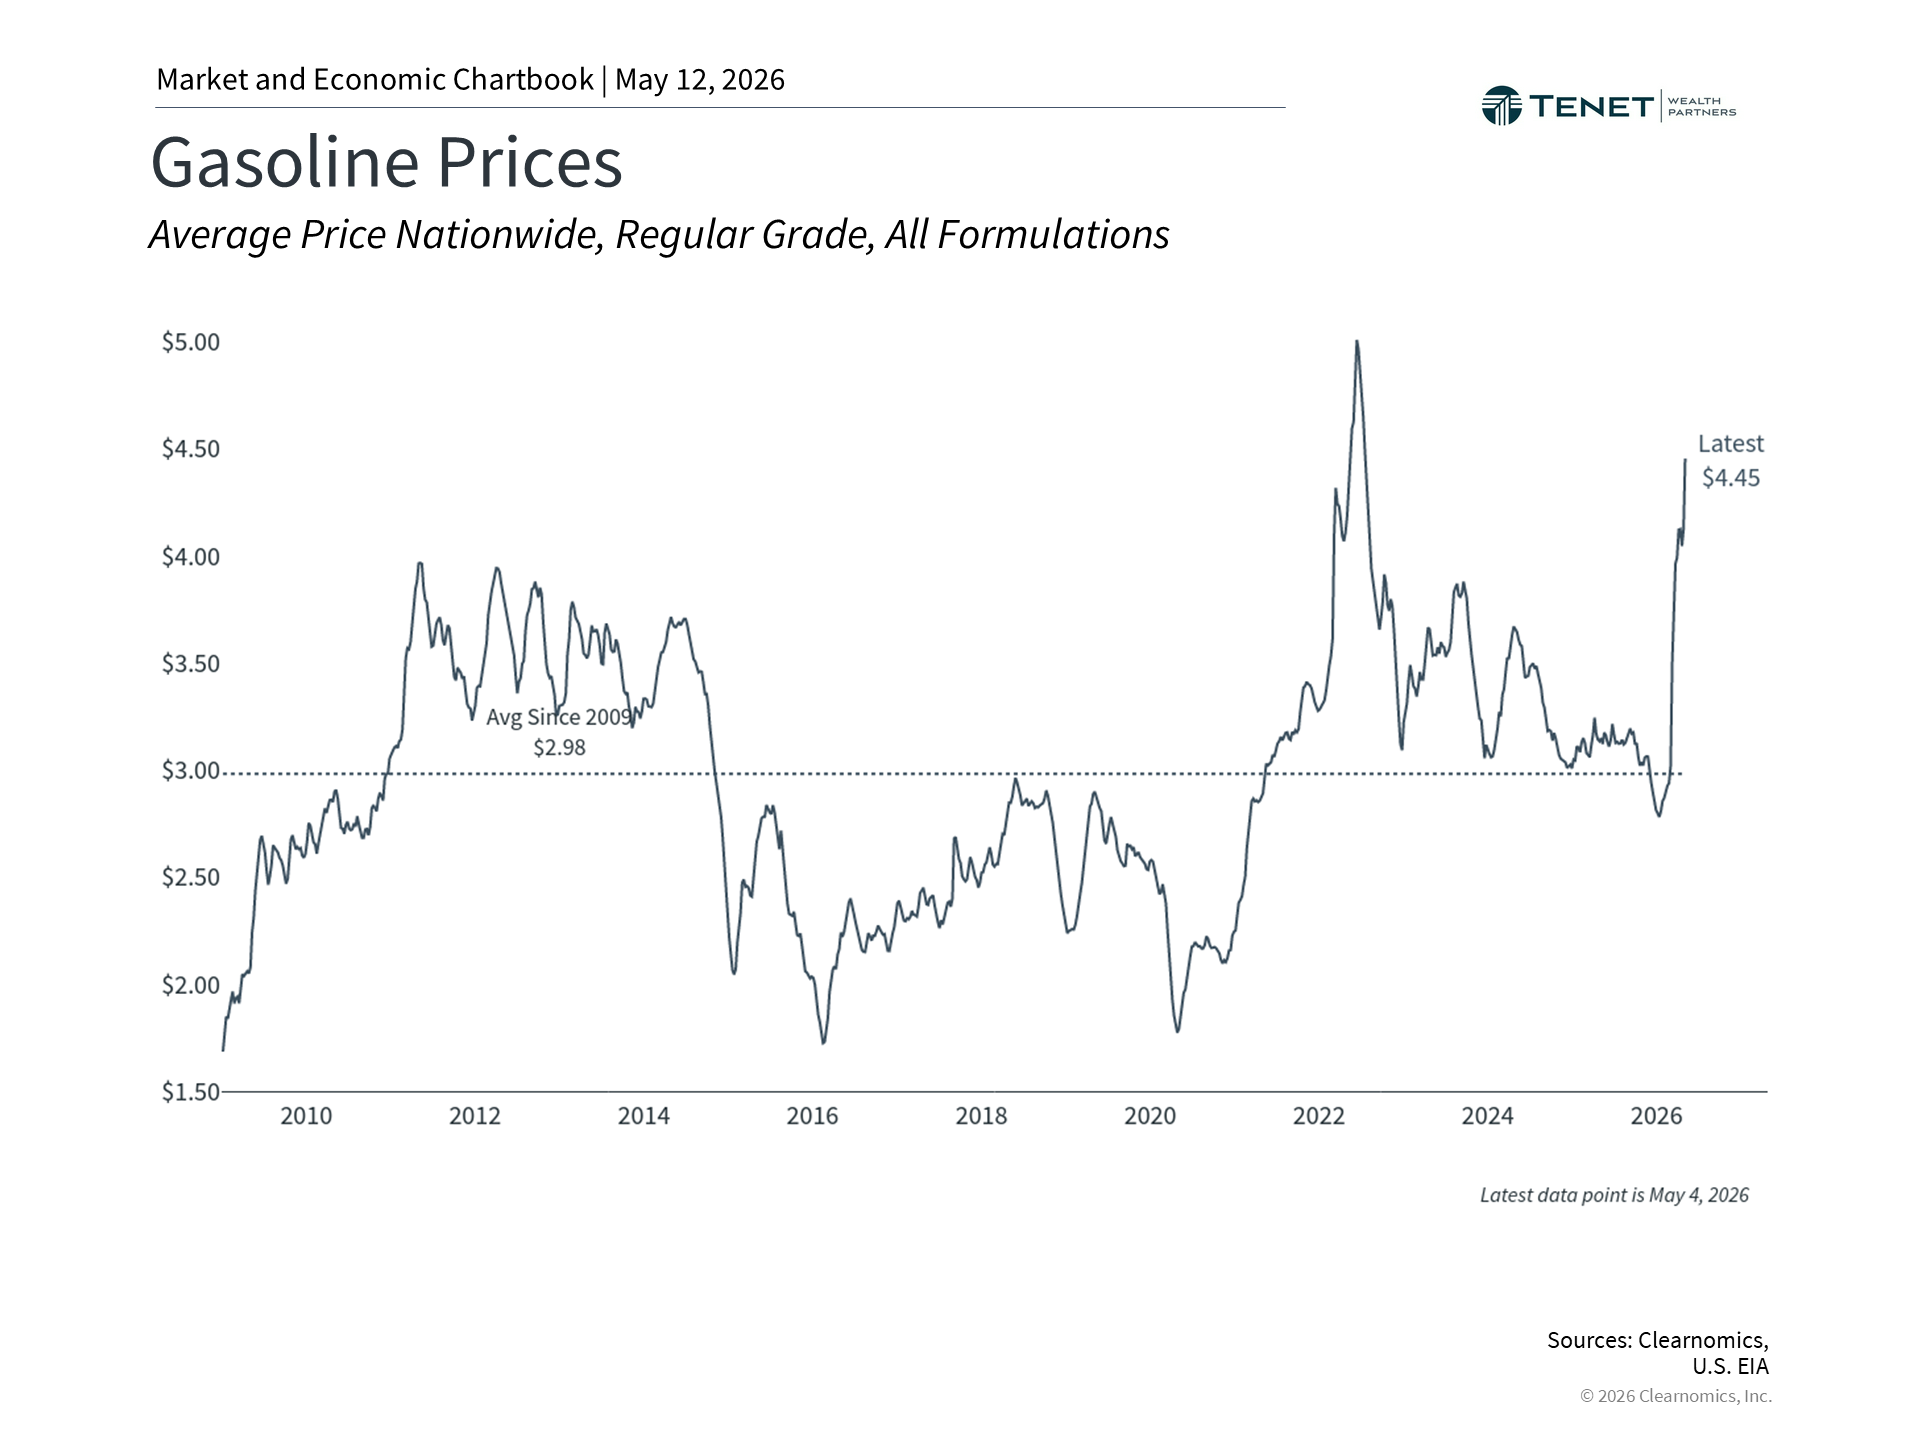 |
One of the most direct ways the conflict in Iran has made itself felt for American households is at the gas pump. The national average for regular unleaded gasoline has risen to approximately $4.50 per gallon, well above the long-term average and a notable increase from levels seen just a few months prior. In certain regions of the country, prices have already surpassed $6 per gallon.1 Because energy costs feed directly into the Consumer Price Index, headline inflation has moved higher, complicating an economic outlook that had previously been on an improving trajectory.
For some observers, this environment may evoke memories of the 1970s Arab Oil Embargo, when supply shocks drove inflation sharply higher and led to gasoline rationing. However, it is important to note that the global energy landscape has changed substantially since that era. The United States is actually now the world’s largest energy producer, extracting more than 13 million barrels of oil per day, which has meaningfully reduced the U.S. economy’s sensitivity to overseas supply disruptions.
The recent decision by the United Arab Emirates (UAE) to exit OPEC further underscores how dramatically the energy landscape has evolved as well. For decades, OPEC members played a central role in setting global oil prices, primarily by coordinating production levels — a task that has proven difficult to enforce across roughly a dozen sovereign nations. In particular, preventing member countries from producing beyond their agreed-upon limits has long been a structural challenge for the organization.
Regardless of the UAE leaving OPEC, individual members have been increasingly prioritizing their own national strategies and production goals. At its height in the 1970s, OPEC accounted for at least half of global oil supply. Today, that share has fallen to approximately one-third.2 To address this decline, the broader OPEC+ coalition — which includes Russia and other non-member producers — was established, though it faces many of the same coordination difficulties.
The reduced relevance of OPEC does not eliminate the risk of oil price spikes during periods of geopolitical stress, but it does suggest that prices are less tightly linked to cartel decisions than in the past. While this offers limited immediate relief to households contending with higher fuel costs, it does help explain why the broader market impact has been relatively contained.
Tariff policy continues to be tested in the courts
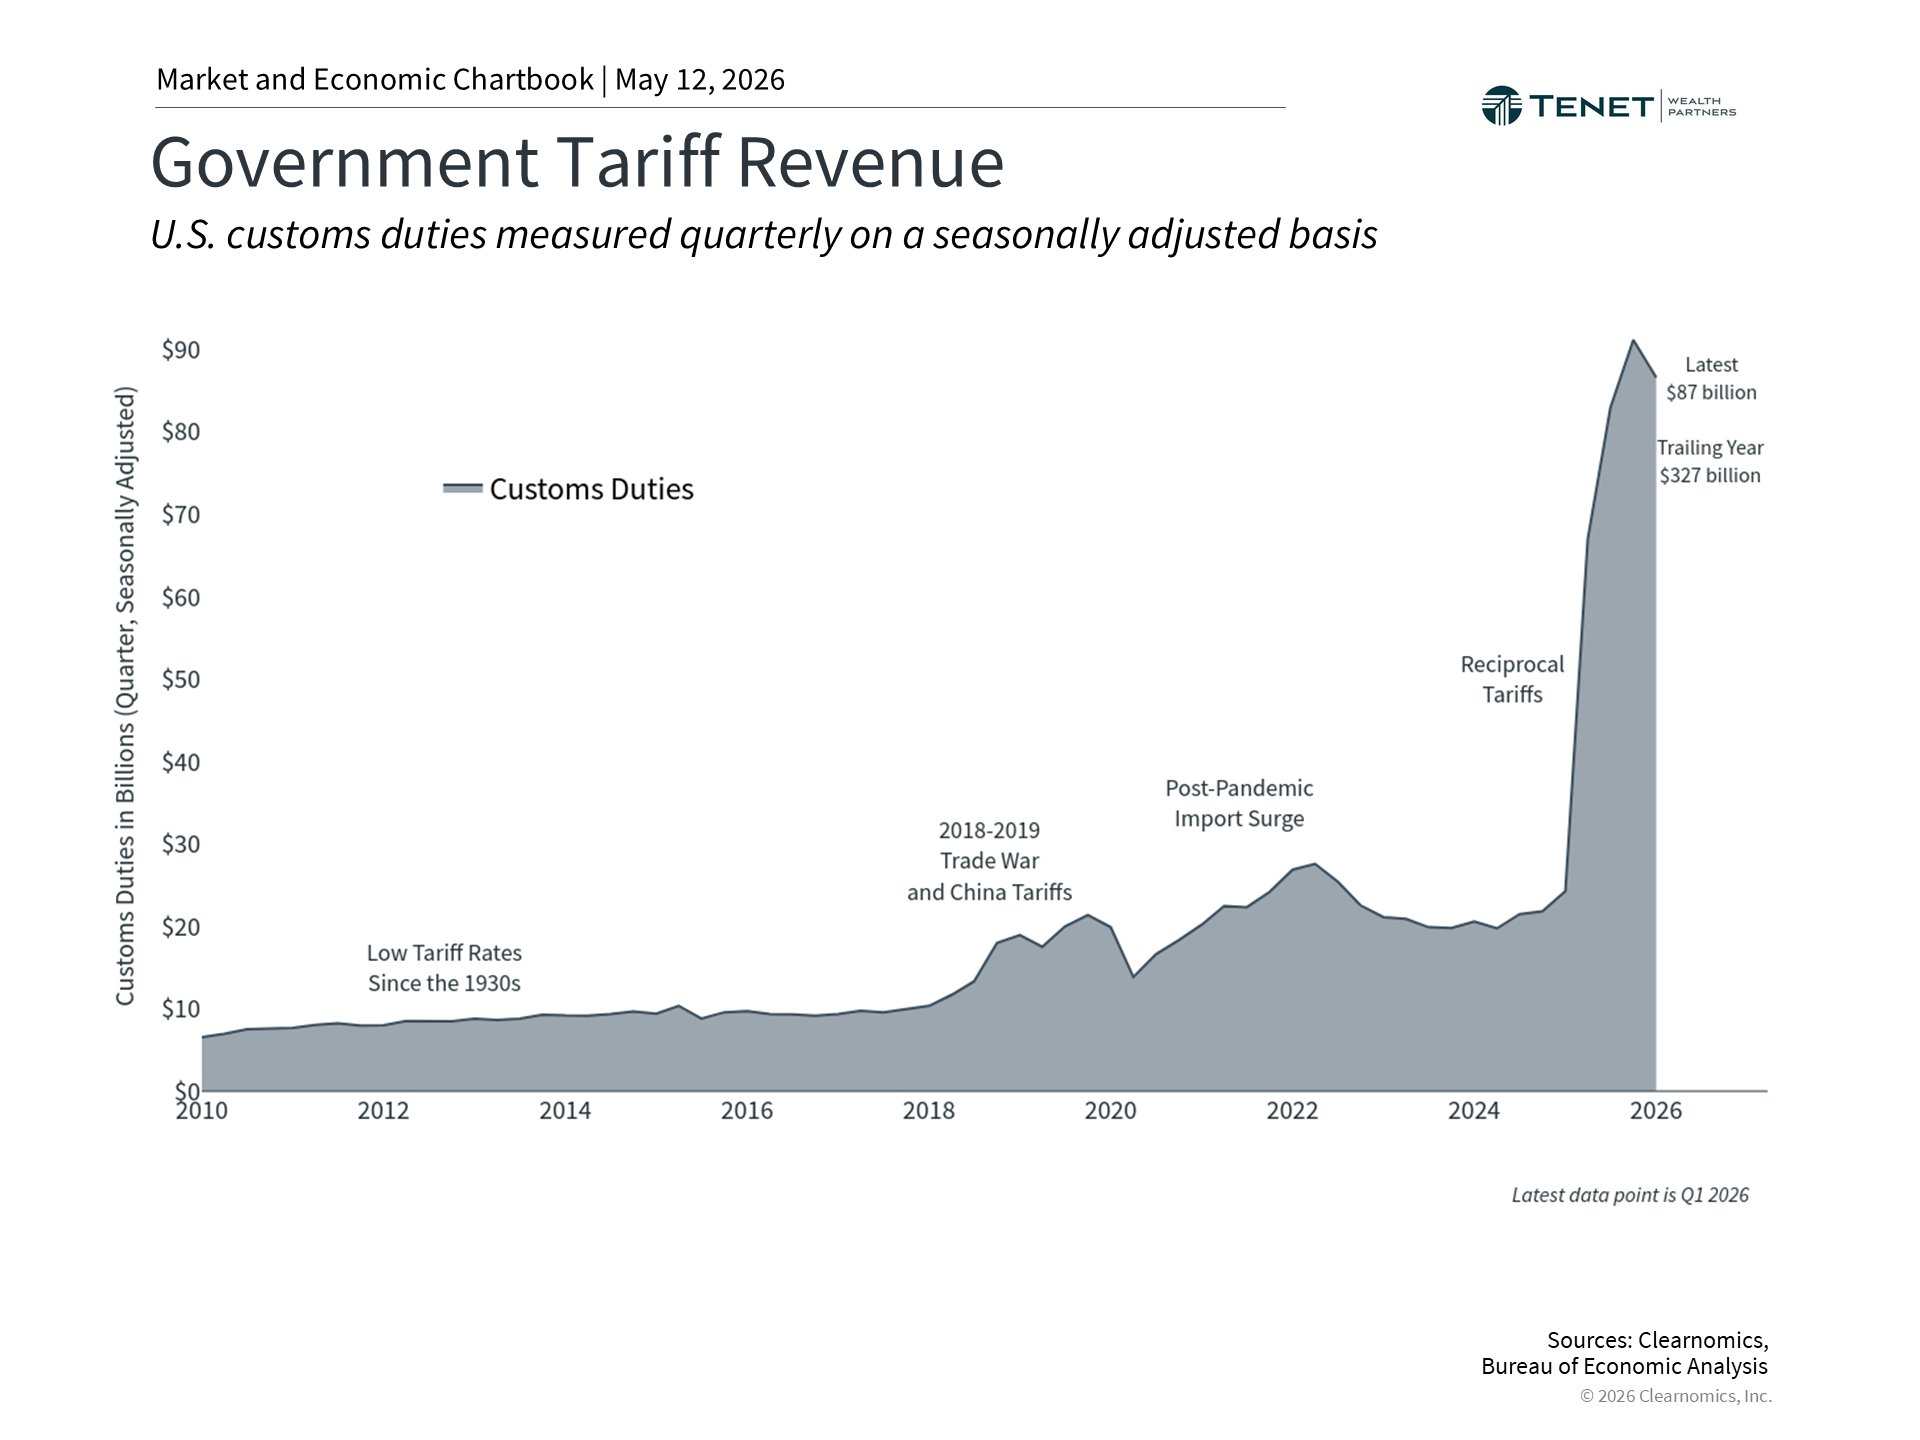 |
The other major macroeconomic force shaping markets has been tariff policy, which has faced a series of legal challenges. In February, the Supreme Court ruled that tariffs implemented the previous April under the International Emergency Economic Powers Act (IEEPA) were illegal.3 In response, the administration moved to implement these tariffs under Section 122 of the Trade Act of 1974 — a measure that the U.S. Court of International Trade has since also ruled unlawful.4
Despite these rulings, the administration has continued to pursue tariffs as a central element of its geopolitical strategy. Other legal authorities remain available, including Section 301 of the Trade Act of 1974, which permits tariffs following formal investigations into specific countries’ trade practices. Such investigations have already been initiated against dozens of countries, indicating that tariffs are likely to persist — potentially in the form of country-specific rates rather than broad measures.
At the same time, the refund process for previously collected tariffs is now underway. Customs and Border Protection has begun processing refund claims, and certain importers have already received payments.5 Estimates suggest that total refunds could fall in the range of $160 to $170 billion.
While the full scope and timeline of refunds remains uncertain, any amounts returned could provide a meaningful boost to earnings and cash flow for the businesses that originally paid them. From a purely economic standpoint, this represents a transfer that was first removed and is now being returned, rather than a net gain. Nevertheless, the effect is broadly positive for both businesses and consumers.
Markets have climbed to record levels despite an uncertain backdrop
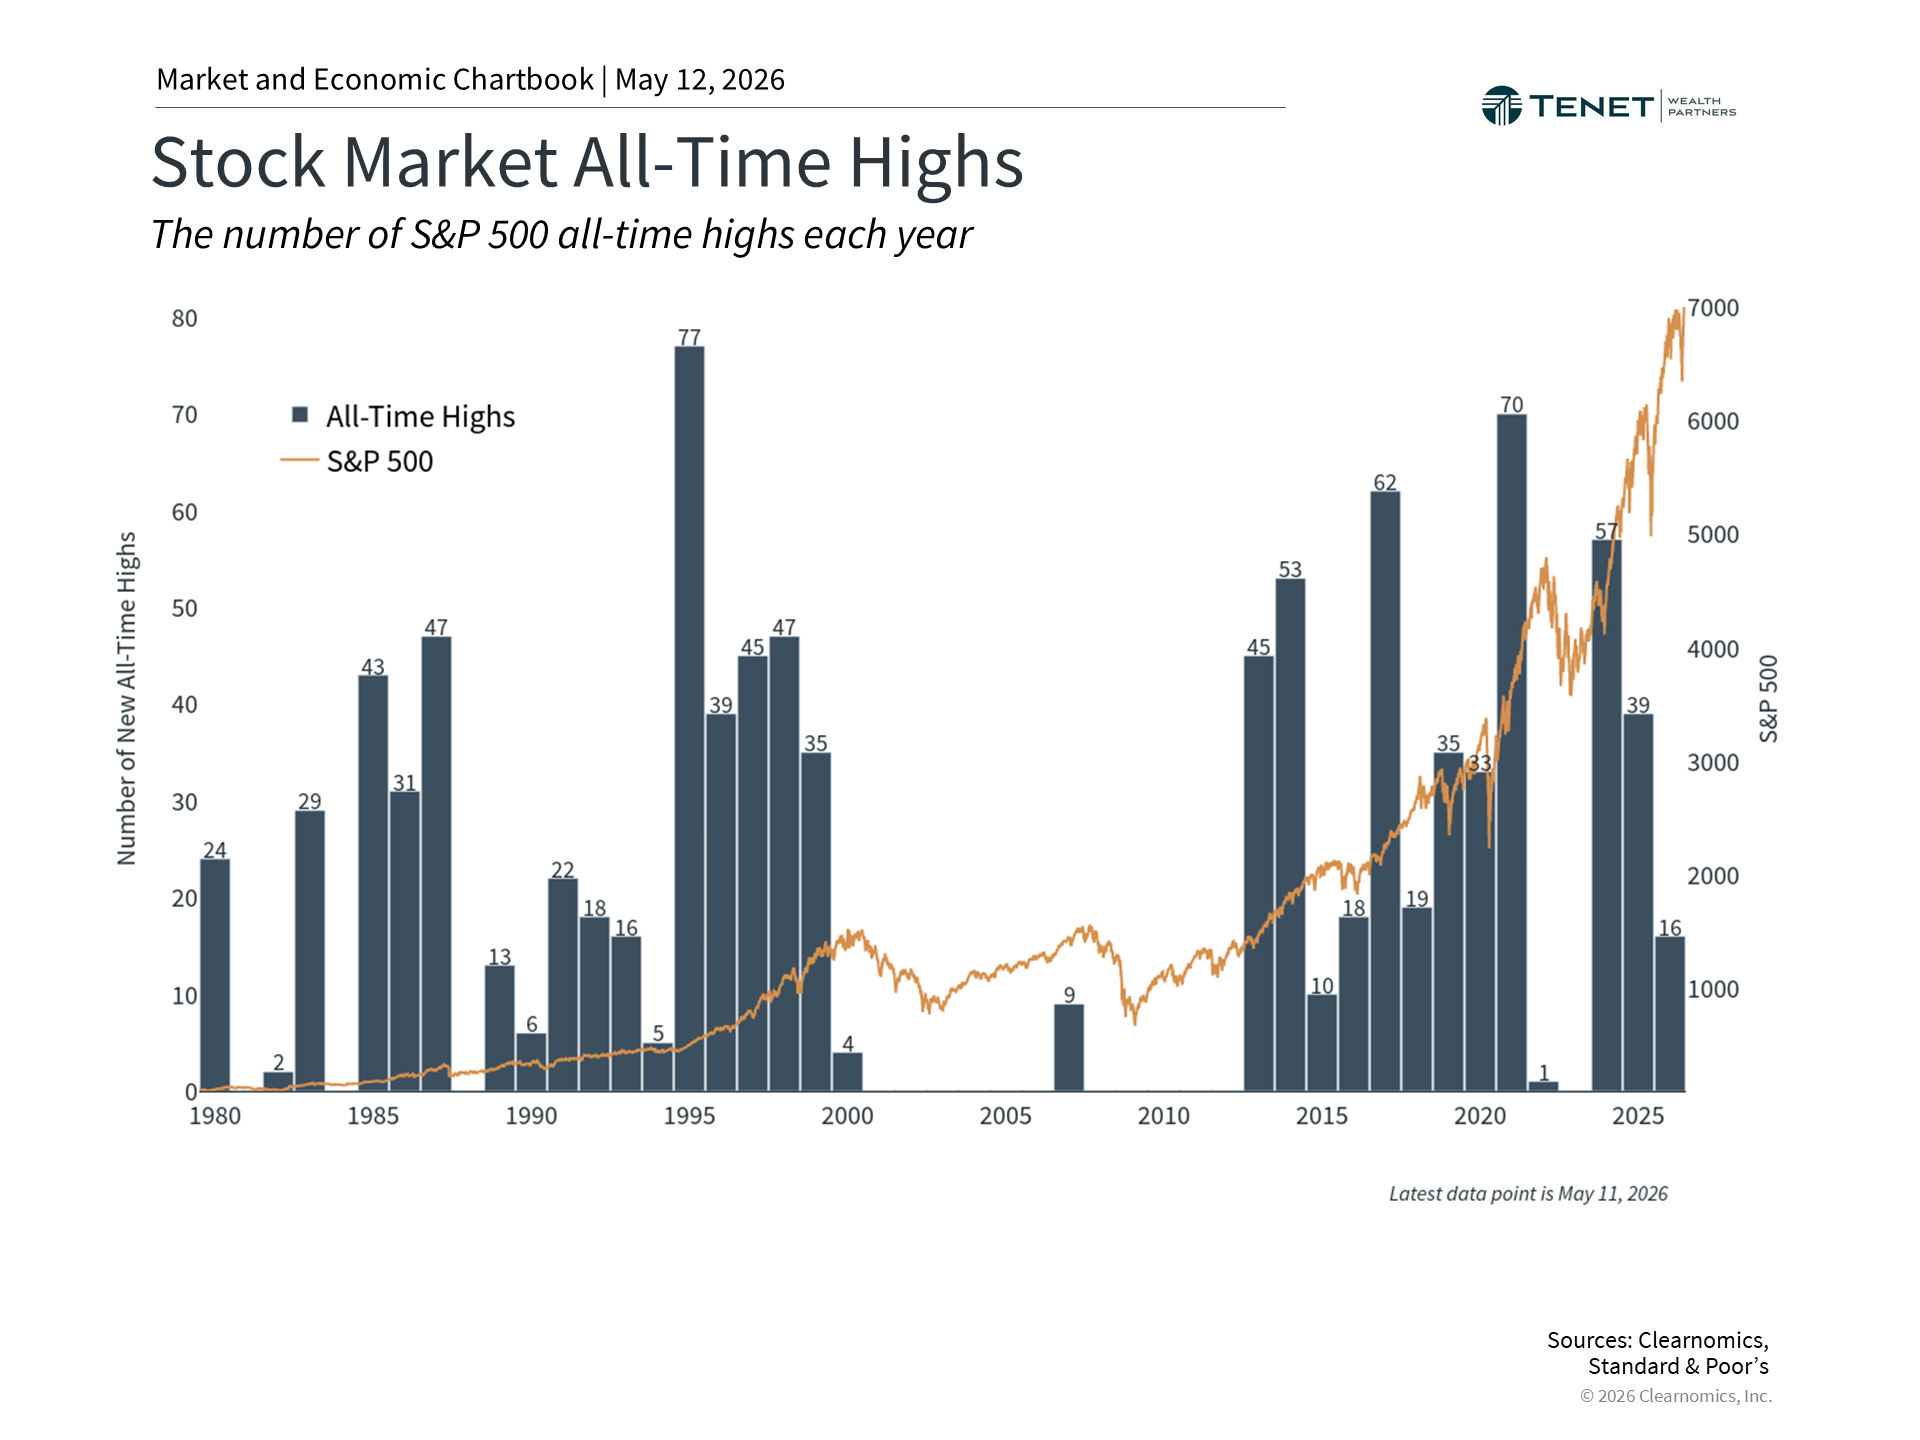 |
For long-term investors, the prevalence of macro-driven events means that broad market indices and individual stocks may move sharply in response to developments like this, even if they have little bearing on any specific company’s underlying performance. That said, another consistent feature of such events is that their market impact tends to diminish as time goes on. Headlines tied to conflicts, energy prices, trade policy, and other concerns may generate short-term volatility, but historically-speaking, they rarely prove to be the defining factors in long-term investment outcomes.
This dynamic helps explain why, despite the considerable uncertainty of the past year and a half, the S&P 500 has still achieved more than a dozen new all-time highs in the current year. As the accompanying chart above illustrates, record highs are a normal occurrence within bull markets, even amid a persistent flow of investor concerns. We believe that what ultimately drives performance is the broader foundation of corporate earnings and economic growth — both of which have remained on solid footing even during this period of short-term market fluctuations.
Overall, today’s market environment is shaped by global forces that tend to come and go. Staying invested with a well-constructed portfolio and remaining focused on your long-term goals remains a prudent way to navigate uncertainty and achieve future outcomes.
Stay Focused Through Market Uncertainty
Headlines will always change — from inflation and tariffs to geopolitical conflict. A thoughtful financial plan is designed to help you stay aligned with your long-term goals through changing market conditions.
No pressure. Just a conversation about your financial future.
References
1. https://gasprices.aaa.com
2. https://www.eia.gov/international/content/analysis/special_topics/Global_Surplus_Crude_Oil_Production_Capacity/full-report.pdf
3. https://www.congress.gov/crs-product/LSB11398
4. https://www.cit.uscourts.gov/sites/cit/files/26-47.pdf
5. https://www.cbp.gov/trade/programs-administration/trade-remedies/ieepa-duty-refunds
Index Description
The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.
Investment advisory services offered through Tenet Wealth Partners, LLC, a registered investment advisor with the U.S. Securities and Exchange Commission. This material is intended for informational purposes only. It should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney or tax advisor. This information is not an offer or a solicitation to buy or sell securities. The information contained may have been compiled from third-party sources and is believed to be reliable.
The information provided in this communication was sourced by Tenet Wealth Partners through public information and public channels and is in no way proprietary to Tenet Wealth Partners, nor is the information provided Tenet Wealth Partner’s position, recommendation or investment advice. Certain statements contained herein may constitute forward-looking statements, which are based on current expectations and subject to change.
This material is provided for informational/educational purposes only. This material is not intended to constitute legal, tax, investment or financial advice. Investments are subject to risk, including but not limited to market and interest rate fluctuations.
Any performance data represents past performance which is no guarantee of future results. Prices/yields/figures mentioned herein are as of the date noted unless indicated otherwise. All figures subject to market fluctuation and change. Additional information available upon request. Index performance is presented for illustrative purposes only and does not represent the performance of any specific investment product or portfolio. An investment cannot be made directly into an index.

About The Author
Kevan Melchiorre, CFP®Co-Founder & Managing Partner
Kevan Melchiorre co-founded Tenet Wealth Partners in 2021 with a focus on delivering a premier client experience, supported by an innovative and fully integrated approach to wealth planning. As a CERTIFIED FINANCIAL PLANNER® practitioner with over 18 years of wealth management experience, Kevan partners with affluent individuals, families, and institutions to help align their capital […]
Learn more about Kevan